Australia’s Big Four Banks: What Borrowers Should Know About Home Loans
Australia’s Big Four Banks
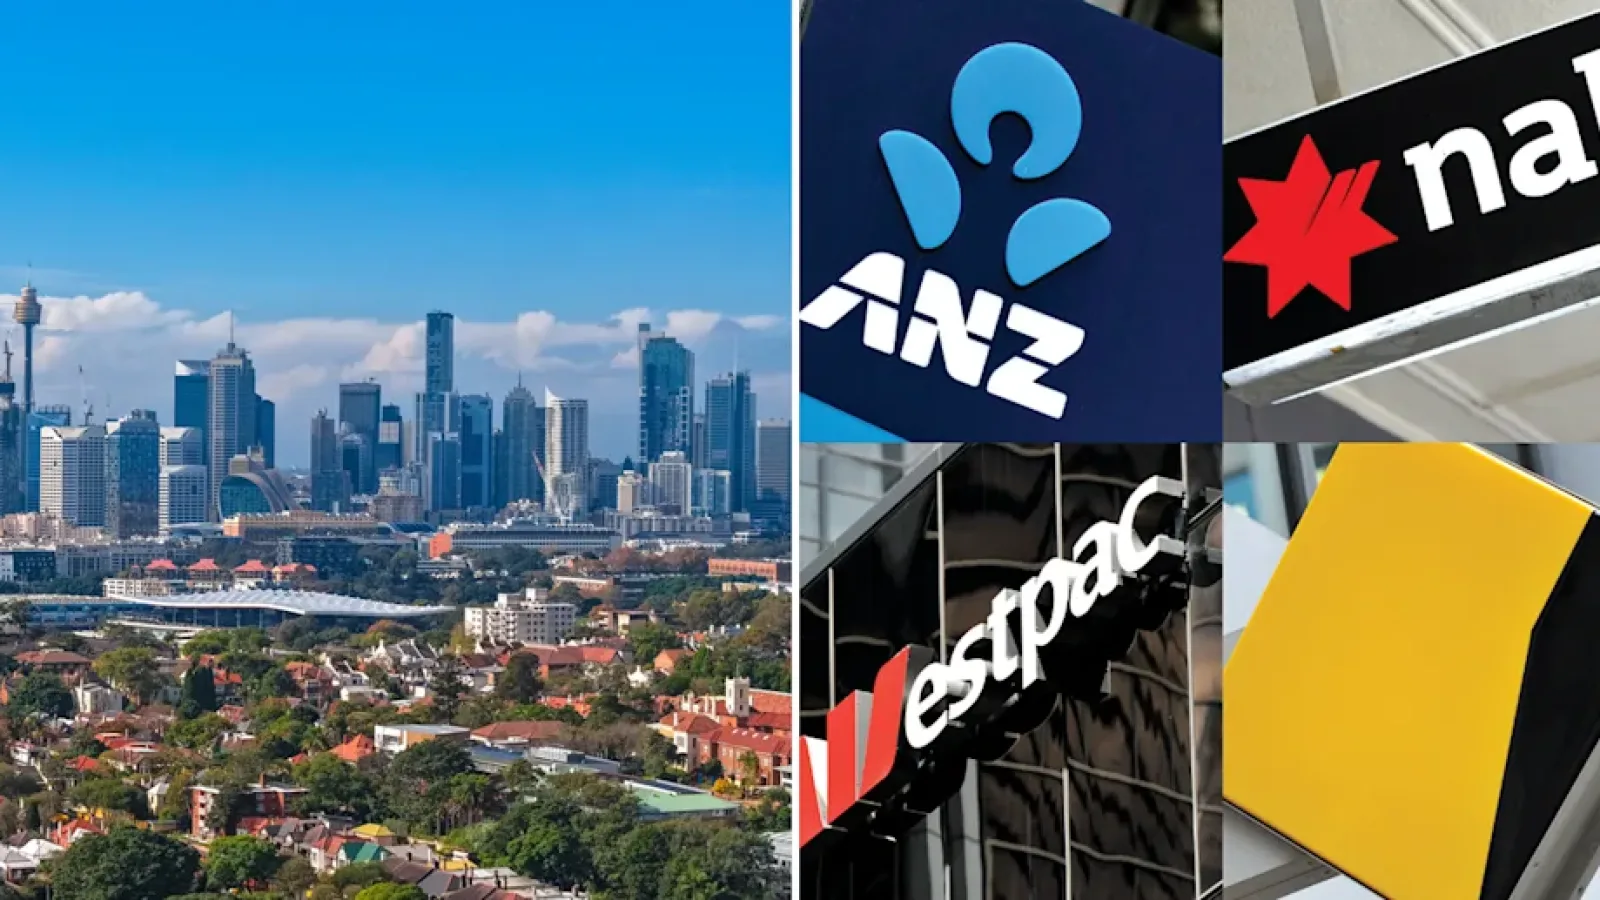
When Australians think about home loans, four major banks often come to mind: ANZ, CommBank, NAB and Westpac.
Together, these banks hold around 70% of Australia's owner-occupied home loan market, making them major players in the country's housing and lending markets.
However, being one of the largest banks does not necessarily mean a lender will offer the most suitable loan for every borrower.
How Do the Major Banks Compare?
Each of the Big Four offers a range of home loan products, including variable and fixed-rate loans.
Some loans may offer features such as:
- Offset accounts to help reduce the interest charged on your loan
- Redraw facilities for accessing eligible additional repayments
- Flexible repayment options
- Fixed-rate periods for greater repayment certainty
- Online tools and digital banking services
The interest rate is also an important consideration, but borrowers should look at the comparison rate, fees and loan features rather than focusing solely on the advertised rate.
Why Does the Interest Rate Matter?
The interest rate on your mortgage can have a significant effect on your repayments and the total amount of interest paid over the life of the loan.
For example, a borrower with a large mortgage could see a noticeable difference in repayments when comparing two loans with different interest rates.
This is why comparing multiple lenders can be worthwhile, even if you already have a preferred bank.
Are the Big Four Always the Cheapest?
Not necessarily.
Smaller banks, credit unions and non-bank lenders also compete in the Australian home loan market and may offer different rates or features.
The biggest lender is not automatically the best lender for every borrower.
A loan that looks attractive because of its interest rate may have different fees, eligibility requirements or features compared with another product.
What Should You Compare?
Before choosing a home loan, consider:
- Interest rate
- Comparison rate
- Upfront and ongoing fees
- Offset and redraw features
- Fixed versus variable repayments
- Loan-to-value ratio requirements
- Flexibility to make additional repayments
Your personal circumstances and financial goals should be considered when comparing home loans.
Choosing the Right Home Loan
Whether you choose one of Australia's Big Four banks or another lender, it is important to understand the terms and costs associated with your loan.
You can use the Crest Finance home loan repayment calculator to estimate your potential repayments and see how different loan amounts, interest rates and loan terms could affect your budget.
Looking Ahead
Australia's home loan market remains competitive, with major banks and smaller lenders continuing to compete for borrowers.
Comparing your options before committing to a mortgage could help you find a loan that better suits your financial circumstances and long-term goals.
This article provides general information only and does not take into account your individual financial circumstances. Consider seeking professional financial advice before making a lending or property decision.